Permanent General Auto Insurance Review (2026)
Our Permanent General auto insurance review explains its role as the underwriter behind The General, with minimum coverage rates starting at $59 per month. Permanent General covers eligible high-risk drivers with traffic violations or insurance gaps and supports SR-22 filings when required by state law.
Read more
Table of Contents
Table of Contents
Insurance and Finance Writer
Merriya Valleri is a skilled insurance writer with over a decade of professional writing experience. Merriya has a strong desire to make understanding insurance an easy task while providing readers with accurate and up-to-date information. Merriya has written articles focusing on health, life, and auto insurance. She enjoys working in the insurance field, and is constantly learning in order to ...
Merriya Valleri
Licensed Insurance Broker
Zach Fagiano has been in the insurance industry for over 10 years, specializing in property and casualty and risk management consulting. He started out specializing in small businesses and moved up to large commercial real estate risks. During that time, he acquired property & casualty, life & health, and surplus lines brokers licenses. He’s now the Senior Vice President overseeing globa...
Zach Fagiano
Updated November 2026
Our Permanent General auto insurance review explains how the company underwrites policies sold through The General, a provider specializing in coverage for high-risk drivers.
- Permanent General underwrites auto insurance for high-risk drivers
- Drivers can buy SR-22 insurance if required
- Policyholders can manage coverage and make payments online
Permanent General is one of several insurers behind The General, offering coverage to drivers with accidents, traffic violations, or insurance lapses.
Permanent General holds an A+ (Superior) financial strength rating from AM Best, reflecting its ability to meet financial obligations. Sentry acquired Permanent General, including The General, in 2025.
Permanent General’s strongest and weakest rating categories should be explained here using the approved table scores. Its financial strength rating does not measure claims satisfaction or customer service.
Drivers searching for affordable auto insurance should check available discounts and compare quotes before buying a policy.
To get a Permanent General insurance quote online and compare rates with other providers, enter your ZIP code into our free quote tool above to get started.
Car Insurance Pricing for High-Risk Drivers
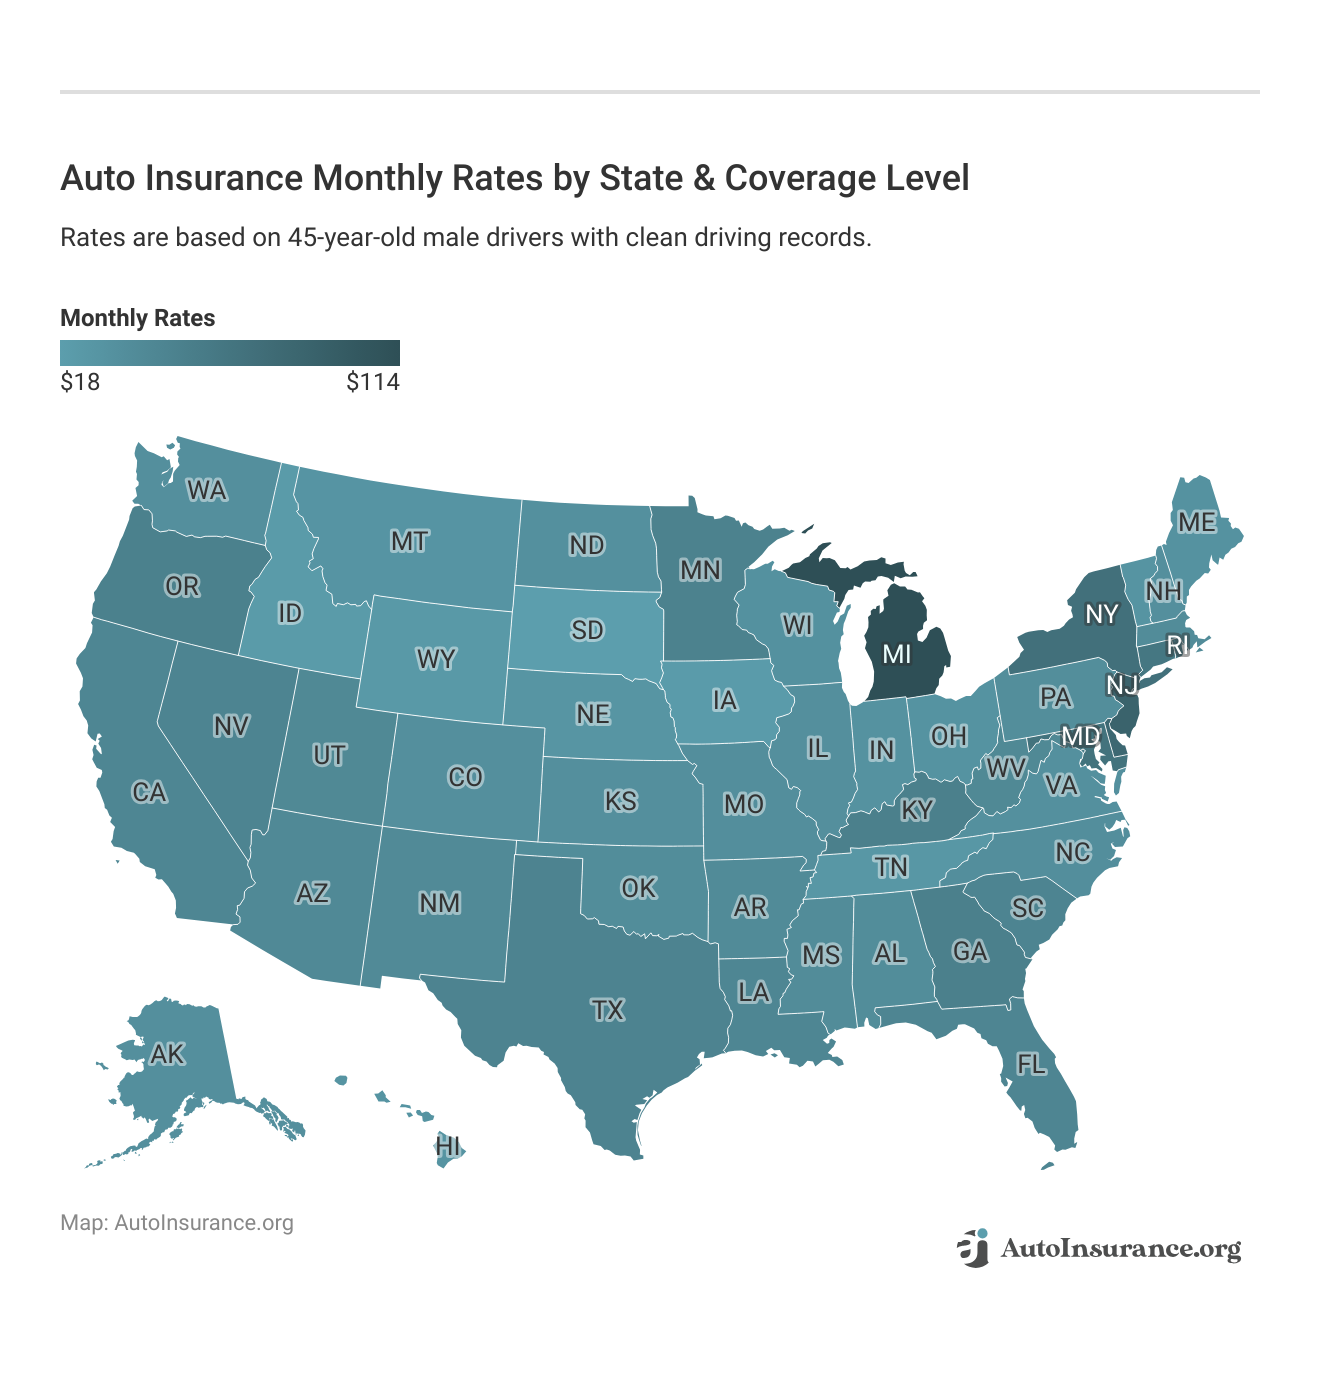
Permanent General Assurance Corporation (PGAC) underwrites some policies sold through The General. The General’s auto insurance rates offer a useful starting point for comparison, but the map below shows The General’s pricing, not rates specific to PGAC.
Your actual premium depends on your driving record, location, coverage, and the insurer issuing your policy. Drivers with DUIs, at-fault accidents, or insurance lapses may pay more because insurers consider them more likely to file claims.

High-risk auto insurance covers drivers who may have difficulty qualifying for standard coverage because of DUIs, accidents, traffic violations, or insurance lapses. These drivers often face higher premiums.
The General’s monthly rates vary by state because insurance requirements, accident frequency, and claims costs differ across locations. The map uses a 45-year-old male driver with a clean driving record.
Drivers in areas with frequent or expensive claims may pay more, even with similar coverage. ZIP codes can also affect premiums within the same state.
Understanding auto insurance rates by state can help explain these differences. Compare quotes using the same coverage limits and deductibles to find suitable coverage.
High-Risk Premiums for Younger vs. Older Drivers
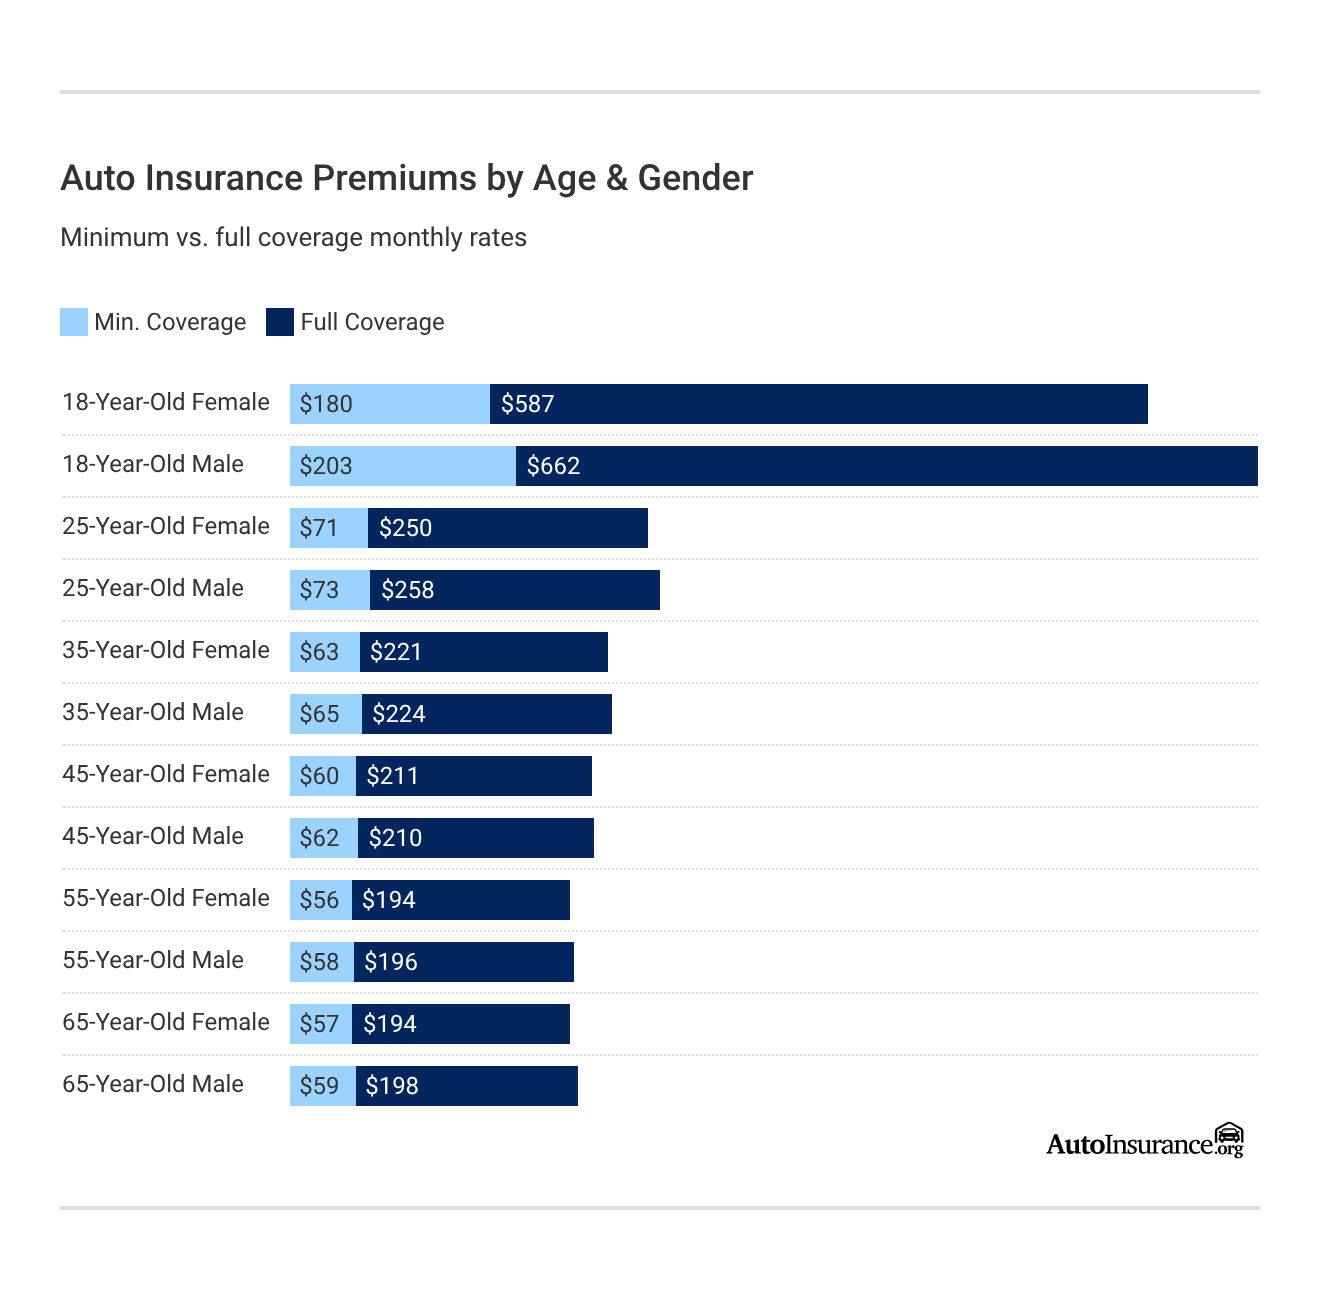
Age and gender can affect car insurance costs. The General’s rate data shows that 18-year-old male drivers pay $203 monthly for minimum coverage, compared with $62 for 45-year-old males. Younger drivers generally pay more because they have less driving experience.
Permanent General considers age, driving history, location, and coverage when setting premiums. The General’s rates provide an estimate, but PGAC pricing varies by driver. Comparing auto insurance rates by age can help explain these differences.
How Coverage Choices Impact Insurance Pricing
Minimum coverage costs less because it meets your state’s liability requirements. Full coverage adds collision and comprehensive protection for your vehicle. Permanent General may charge higher premiums for drivers with DUIs, accidents, or insurance lapses, especially when they choose more coverage. Understanding how much car insurance you need can help you choose suitable limits.
How Traffic Violations Change Auto Insurance Costs
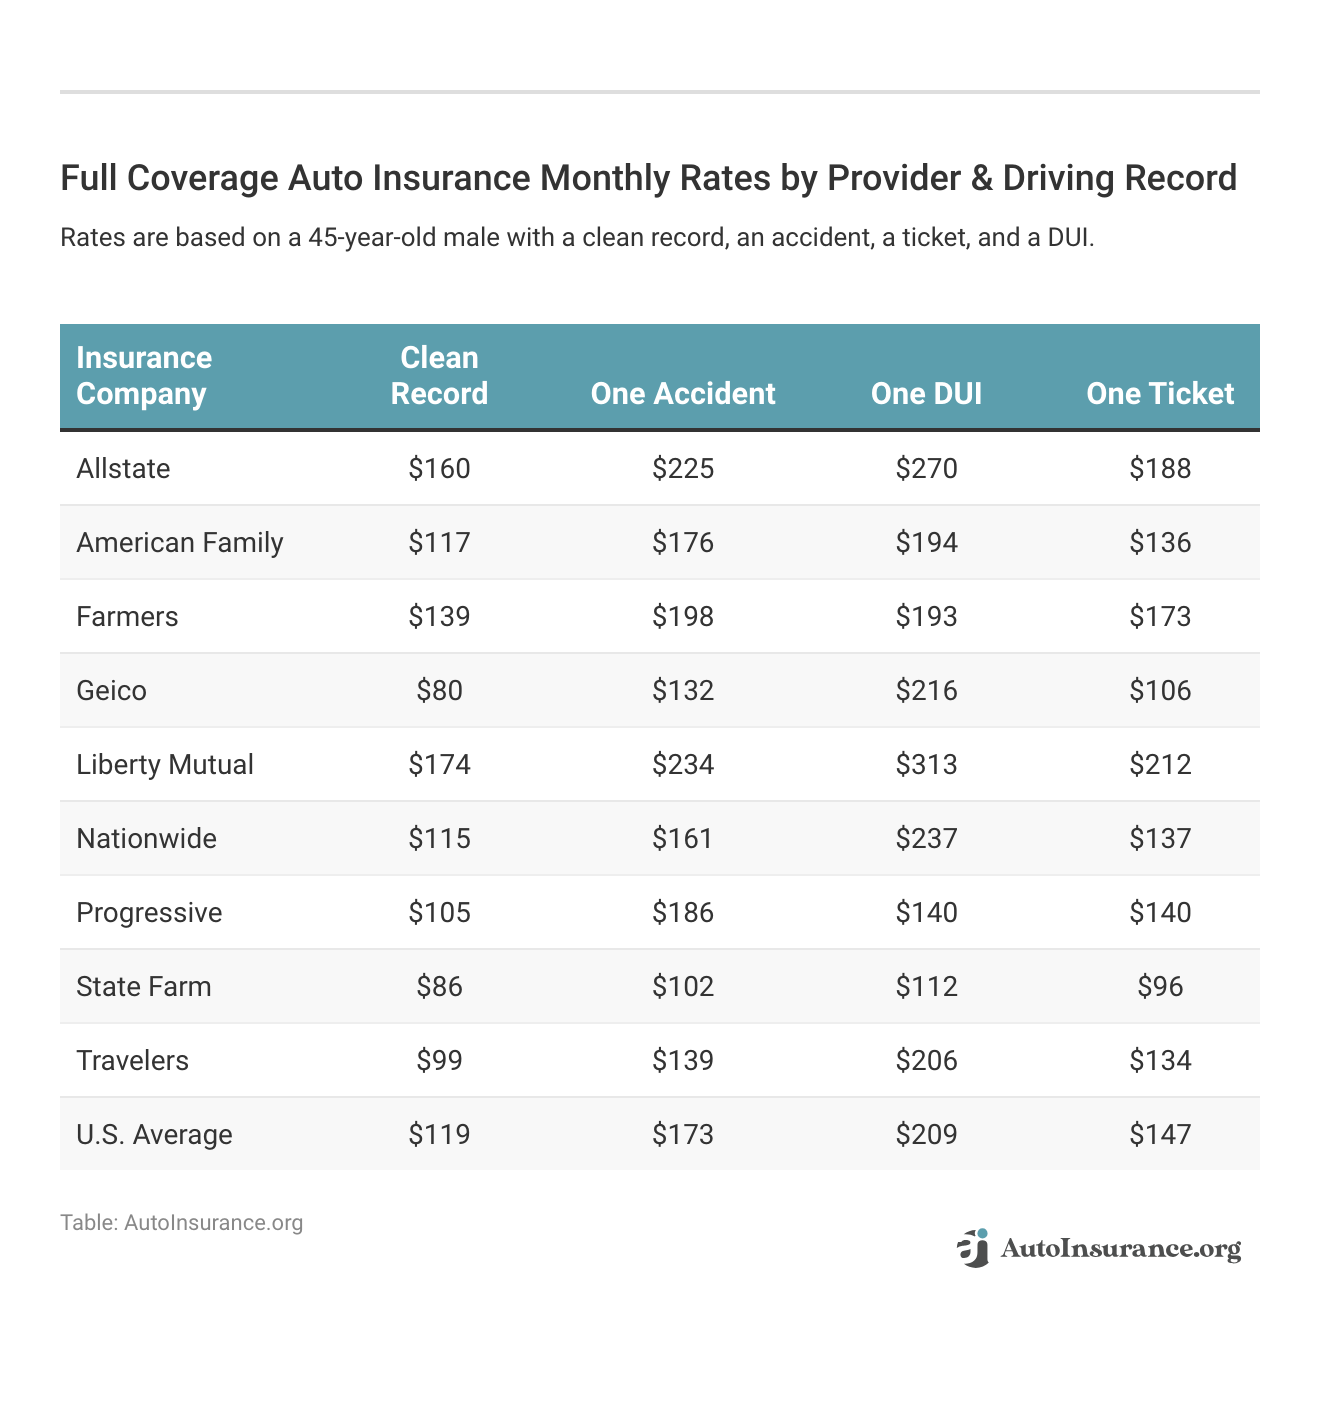
Your driving history plays a major role in how much you pay for car insurance. Drivers with accidents, DUIs, or speeding tickets may face higher premiums than those with clean records.
However, premiums can increase after an accident, DUI, or speeding ticket because PGAC, as the underwriter, considers these incidents when calculating risk.
Permanent General specializes in coverage for drivers who may need high-risk auto insurance after past violations.
The rates shown are based on a 45-year-old male driver with excellent credit and minimum coverage. Actual premiums vary by driving record, so enter your ZIP code into our free comparison tool to find quotes from available insurers that match your profile.
Credit-Based Pricing at Permanent General
Credit history can influence Permanent General auto insurance premiums in states that permit credit-based pricing. Drivers with excellent credit generally pay lower monthly rates, while those with fair or poor credit may face higher costs for the same coverage.
Insurers may use an auto insurance score to predict claims in states that allow it. Poor credit can raise premiums or limit coverage options. Permanent General may insure eligible high-risk drivers through The General, depending on their circumstances.
Free Insurance Comparison
Compare Quotes From Top Companies and Save
A Closer Look at Permanent General’s Reputation
When choosing an auto insurance company, consider financial strength and customer complaints. AM Best measures financial stability, while the BBB tracks business complaints and the NAIC compares insurer complaint levels.
Permanent General holds an A+ (Superior) AM Best rating. Sentry acquired The General and PGAC in 2025, so some financial ratings may reflect Sentry rather than Permanent General.
Financial ratings indicate an insurer’s ability to pay covered claims, while complaint data can reveal customer concerns about service, communication, and claims handling. Neither measure alone establishes how satisfied policyholders are with the claims process.
Permanent General underwrites policies sold through The General, which handles payments, enrollment, documents, renewals, policy changes, and cancellations online or through its representatives.
How to File a Permanent General Insurance Claim
Permanent General is responsible for covered claims on policies it issues, while The General provides customer-facing claims services. Policyholders can file claims online, through The General’s app, or by phone.
To file a claim through The General:
- Report the Accident: Contact The General and provide the accident details.
- Submit Documents: Share your policy number, photos, and any available police reports.
- Track Your Claim: Check its status online or contact your claims representative.
For the current PGAC insurance claims phone number, check your policy documents or The General’s official website.
PGAC’s AM Best rating measures financial strength, not claims processing speed or customer satisfaction. Knowing how to file an auto insurance claim can help you prepare before reporting an accident.
How to Save on Permanent General Auto Insurance
Drivers with Permanent General policies may lower their insurance costs through safer driving, coverage adjustments, and payment choices available through The General.
- Avoid New Violations: Maintain a clean driving record to avoid premium increases from tickets or accidents.
- Choose Flexible Payments: The General offers monthly installments and flexible billing options, though these may not reduce premiums.
- Compare Quotes at Renewal: Check rates from other insurers before renewing to see whether you can get a lower premium.
- Increase Your Deductibles: Choosing a higher deductible may lower your premium, but you’ll pay more toward covered claims.
- Maintain Continuous Coverage: Avoid policy lapses that could increase future insurance costs.
- Increase Your Deductibles: A higher deductible may lower premiums, but you’ll pay more after a covered claim. Learn how auto insurance deductibles affect your costs.
The General advertises discounts for multiple vehicles, vehicle safety features, and continuous coverage. Paying in full may also reduce premiums. These discounts depend on eligibility and may not apply to every PGAC-underwritten policy.
Drivers considering upfront payment can learn more about pay-in-full auto insurance discounts before choosing a payment plan. Contact The General to confirm which discounts apply to your policy and whether any documentation is required.
How Permanent General Covers High-Risk Drivers
Permanent General Assurance Corporation (PGAC) underwrites policies sold through The General, which helps high-risk drivers with DUIs, traffic violations, accidents, or insurance lapses find coverage when standard insurers turn them down.
PGAC policies sold through The General may include minimum liability or full coverage with collision and comprehensive insurance. Depending on the state and eligibility, additional options and services may include:
- Commercial Auto: Coverage options for eligible vehicles used for business purposes.
- Gap Coverage: Helps cover the difference between a vehicle’s loan balance and its insurance payout after a covered total loss.
- Mexico Travel: Additional coverage options for eligible drivers traveling into Mexico.
- Roadside Assistance: Third-party assistance for towing, jump-starts, and other roadside emergencies, separate from PGAC underwriting.
- SR-22 Filings: SR-22 auto insurance is proof of coverage filed with the state, rather than a separate policy.
Drivers with PGAC-underwritten policies may qualify for an SR-22 filing through The General, depending on their state and eligibility. For affordable filing options, see our guide to cheap SR-22 auto insurance.
An SR-22 confirms that a driver carries the required insurance after certain violations or license suspensions. Filing requirements and how long drivers must maintain coverage vary by state.
Drivers who need an SR-22 should confirm their state’s minimum liability limits, filing requirements, and required coverage period before purchasing insurance.
They must also keep their policy active throughout that period, as a coverage lapse could delay license reinstatement or lead to another suspension.
Check your state's SR-22 filing requirements, confirm the required liability limits, and keep your insurance active throughout the filing period to avoid problems with your driving privileges.Jeff Root Licensed Insurance Agent
Coverage eligibility depends on your state, driving history, previous violations, and the insurer underwriting your policy. Some optional benefits may not be available with every PGAC policy.
Enter your ZIP code into our free comparison tool to find available insurers and compare quotes for the coverage you need.
Free Insurance Comparison
Compare Quotes From Top Companies and Save
Key Considerations for PGAC Insurance
Permanent General may offer more flexible underwriting for eligible drivers with DUIs, traffic violations, or insurance lapses. Its policies are sold through The General, which also provides online policy management and flexible payment options.
The pros and cons below reflect PGAC-underwritten policies sold through The General. Availability, pricing, and coverage options depend on the driver’s state and history.
Drivers with past violations should confirm their coverage eligibility and SR-22 filing requirements with The General before purchasing a policy.Brandon Frady Licensed Insurance Producer
One drawback is the limited information available about PGAC separately from The General. Customers may need to contact The General or check their policy documents to confirm underwriting details, coverage restrictions, and claims information.
High-risk insurance may help drivers with serious violations who can’t get standard coverage. Explore the best non-standard insurance companies for other options. Permanent General rates vary by driving history, coverage, and location.
Choosing Permanent General Car Insurance
Our Permanent General auto insurance review finds that PGAC may be worth considering for high-risk drivers who struggle to qualify for coverage. PGAC underwrites policies through The General but isn’t a separate brand drivers can shop through.
Drivers who need SR-22 filings after violations or license suspensions may find coverage options through The General. PGAC’s financial strength rating reflects its ability to pay covered claims, while The General handles customer-facing claims services.
Before buying, learn how to get multiple auto insurance quotes using the same coverage limits and deductibles. A policy that meets state requirements may not offer the lowest price or the protection you need.
Start shopping around for high-risk coverage by entering your ZIP code into our free quote comparison tool below and see if The Permanent General Assurance Corp is your best choice.
Frequently Asked Questions
Is Permanent General Assurance Corporation the same as The General?
No. Permanent General Assurance Corporation (PGAC) is an insurance underwriter, while The General is the brand customers use to get quotes, purchase policies, and manage coverage. PGAC may appear as the legal insurer on policies sold through The General.
What is Permanent General Assurance Corporation (PGAC)?
Permanent General Assurance Corporation underwrites auto insurance policies sold through The General, including coverage for drivers with DUIs, traffic violations, or insurance lapses. Applicants should prepare the documents needed for car insurance before requesting coverage.
Who owns Permanent General auto insurance?
Sentry acquired Permanent General and its affiliated insurance operations, including The General, in 2025. PGAC continues to underwrite eligible policies sold through The General.
Does Permanent General insure high-risk drivers?
Yes. PGAC may insure drivers with DUIs, accidents, speeding tickets, or coverage lapses through The General. Approval and premiums depend on driving history, location, and eligibility. Drivers with previous accidents may also wonder whether an insurer can drop them after a claim.
A better price may be out there. Shop car insurance quotes to find a policy that fits your budget.
Does Permanent General offer SR-22 insurance?
PGAC may underwrite policies that support SR-22 filings through The General. An SR-22 confirms that a driver carries the required liability insurance and isn’t a separate policy. Filing fees, requirements, and coverage periods vary by state.
How do I file a Permanent General auto insurance claim?
File a claim through The General’s website, mobile app, or customer service department. Provide your policy number, accident details, and supporting documents. The General handles customer-facing claims services, while PGAC is responsible for covered claims on policies it underwrites. State deadlines determine how long after an accident you can file a claim.
How can I get a Permanent General auto insurance quote?
Visit The General’s website or contact its representatives to request a quote. Enter your ZIP code, vehicle information, driving history, and preferred coverage. Check your policy documents to confirm whether PGAC is the underwriter.
What types of auto insurance coverage does PGAC offer?
PGAC underwrites non-standard auto insurance policies sold through brands such as The General, helping eligible high-risk drivers obtain coverage. Policies may include liability, collision, comprehensive, uninsured motorist, and other state-specific protections. Vehicle value, repair costs, and premiums can influence when to drop full coverage auto insurance.
For cheaper coverage, review car insurance pricing to get started.
How much does Permanent General auto insurance cost per month?
PGAC is an underwriter, so The General is a good place to start when requesting a quote. The General’s minimum coverage rates start at $59 per month in the article’s data, but this isn’t a verified PGAC-specific rate. Drivers with DUIs, accidents, or insurance lapses may pay more because insurers consider these risks when calculating premiums.
Is Permanent General a reliable insurance company?
Permanent General holds an A+ (Superior) financial strength rating from AM Best, reflecting its ability to meet financial obligations. However, this rating doesn’t measure claims satisfaction or processing speed. Checking whether an auto insurance company is legitimate can also help drivers assess an insurer before purchasing coverage.
What auto insurance discounts does Permanent General offer?
Is Permanent General auto insurance available in every state?
Can Permanent General customers manage their insurance policies online?
Get a FREE Quote in Minutes
Insurance rates change constantly — we help you stay ahead by making it easy to compare top options and save.