Best Auto Insurance With Annual Payments: Top 10 Companies Ranked (2026)
Erie, Nationwide, and State Farm offer the best auto insurance with annual payments, and Auto-Owners has the lowest minimum-coverage rate at $624 per year. Erie’s Rate Lock can help limit premium increases, Nationwide’s SmartRide offers eligible drivers savings of up to 40%, and State Farm’s Steer Clear rewards qualifying drivers under 25.
Read more
Table of Contents
Table of Contents
Managing Editor
Laura Kuhl holds a Master’s Degree in Professional Writing from the University of North Carolina at Wilmington. Her career began in healthcare and wellness, creating lifestyle content for doctors, dentists, and other healthcare and holistic professionals. She curated news articles and insider interviews with investors and small business owners, leading to conversations with key players in the le...
Laura Kuhl
Head of Content
Meggan McCain, Head of Content, has been a professional writer and editor for over a decade. She leads the in-house content team at Quote.com. With three years dedicated to the insurance industry, Meggan combines her editorial expertise and passion for writing to help readers better understand complex insurance topics. As a content team manager, Meggan sets the tone for excellence by guiding c...
Meggan McCain
Licensed Auto Insurance Agent
Daniel Walker graduated with a BS in Administrative Management in 2005 and has run his family’s insurance agency, FCI Agency, for over 15 years (BBB A+). He is licensed as an insurance agent to write property and casualty insurance, including home, life, auto, umbrella, and dwelling fire insurance. He’s also been featured on sites like Reviews.com and Safeco. To ensure our content is accura...
Daniel Walker
Updated October 2026
Erie, Nationwide, and State Farm are our top three picks for having the best auto insurance with annual payments.
- Erie helps keep premiums steady at renewal with Rate Lock
- Nationwide offers up to 40% savings through SmartRide
- Annual payments may help avoid monthly installment fees
Erie’s Rate Lock can help limit changes to your premium at renewal, while paying in full may provide separate savings if an eligible discount is available.
Nationwide’s SmartRide tracks driving habits like braking and acceleration, offering eligible drivers up to 40% in savings. You can also check whether paying your premium upfront reduces your total cost.
Top 10 Companies: Best Auto Insurance With Annual Payments
| Company | Rank | Claims Satisfaction | AM Best | Best for |
|---|---|---|---|---|
| Erie | #1 | 743 / 1,000 | A | Rate Stability |
| Nationwide | #2 | 729 / 1,000 | A | Low Mileage |
| State Farm | #3 | 716 / 1,000 | A+ | Discount Variety |
| Auto-Owners | #4 | 711 / 1,000 | A+ | Agent Support |
| American Family | #5 | 702 / 1,000 | A | Loyalty Rewards |
| Geico | #6 | 697 / 1,000 | A++ | Online Savings |
| Allstate | #7 | 693 / 1,000 | A+ | Deductible Cuts |
| Travelers | #8 | 691 / 1,000 | A++ | Driver Tracking |
| Farmers | #9 | 690 / 1,000 | A | Policy Flexibility |
| Progressive | #10 | 673 / 1,000 | A+ | Risky Drivers |
State Farm’s Steer Clear rewards eligible drivers under 25 who complete its training program and meet safe-driving requirements.
Enter your ZIP code to compare yearly car insurance rates from providers in your area and find coverage that fits your budget and driving needs.
Understanding Annual Auto Insurance Policies
If you cancel an annual car insurance policy early, your insurer may charge a cancellation fee or refund the unused portion of your premium.
If you’ve already paid in full, ask how much you’d get back. It’s worth knowing these terms before committing to a policy.
How Policy Length Affects Car Insurance Costs and Renewals
Six-month and annual policies mainly differ in how often they renew. With semi-annual car insurance premiums, you’ll generally have two renewal periods each year instead of one.
With annual auto insurance, your rate is generally set for 12 months unless you make changes to your policy.
Annual vs. Semiannual Auto Insurance Policies
| Feature | 6-Month | 12-Month |
|---|---|---|
| Best for | Flexibility | Rate stability |
| Discounts | May qualify | May qualify |
| Payments | Full or monthly | Full or monthly |
| Rate Changes | More frequent | Less frequent |
| Renewals | Twice yearly | Once yearly |
| Rate Stability | Shorter protection | Longer protection |
A six-month policy renews sooner, so your rate can be adjusted earlier based on updated pricing factors.
Before choosing, compare the total cost of car insurance for a year under each option. A lower six-month auto insurance rate to start may end up costing more if the price goes up at renewal.
Benefits of Choosing an Annual Auto Insurance Policy
A 12-month policy gives you more time between renewals. Your rate is generally set for the term unless you change your car, drivers, or coverage.
Here are a few key benefits of choosing a full-year auto insurance policy:
- Easier Budgeting: Knowing your premium for the policy term can make planning your insurance costs simpler.
- Fewer Renewals: A 12-month policy renews once a year instead of twice.
- Later Rate Changes: New tickets or at-fault accidents may not affect your premium until your next renewal.
- Longer Rate Period: Your premium is generally set for 12 months unless you change your policy.
- Pay-in-Full Savings: Paying upfront may qualify you for a discount if your insurer offers one.
If you prefer fewer renewals, one-year car insurance options may be worth considering. Check the full annual cost, coverage, deductible, and available savings before choosing a policy term.
You can also check online auto insurance quotes to see how insurers price similar coverage before making your choice.
Comparing Annual Car Insurance Costs
Insurers consider your driving history, age, car, ZIP code, and coverage level when determining your annual premium. Because of these factors, the average cost of auto insurance may not reflect what you’ll actually pay for yearly insurance.
The same driver can get different rates when comparing yearly insurance for cars from one insurer to another, even with similar coverage.
Choosing a higher deductible can lower your annual premium, but you’ll pay more out of pocket if you file a covered claim.
Bundling, safe driving, and low annual mileage may help you save without cutting back on your insurance protection.
When comparing annual policies, ask for the total 12-month cost with and without installment fees. A lower monthly payment doesn't necessarily mean a cheaper policy.Justin Wright Licensed Insurance Agent
Adding a driver, buying a new car, or moving to a different ZIP code can change your premium, so let your insurer know when something changes.
Before renewal, compare quotes to see if another insurer offers a lower rate or more ways to save.
Choosing Between Minimum and Full Coverage Insurance
The coverage you choose can make a big difference in what you pay for car insurance each year. Minimum coverage typically includes the liability insurance your state requires, so it usually costs less than full coverage.
Full coverage adds collision and comprehensive protection to help pay for damage to your car. You’ll pay more for these added protections, whether you pay your premium monthly or annually.
Yearly Premiums for Auto Insurance by Coverage Level
| Insurance Company | Minimum Coverage | Full Coverage |
|---|---|---|
| Allstate | $936 | $2,100 |
| American Family | $828 | $1,884 |
| Auto-Owners | $624 | $1,440 |
| Erie | $672 | $1,536 |
| Farmers | $888 | $2,064 |
| Geico | $660 | $1,512 |
| Nationwide | $756 | $1,812 |
| Progressive | $852 | $1,992 |
| State Farm | $708 | $1,596 |
| Travelers | $840 | $1,920 |
Have a newer car or an active auto loan? Your lender generally requires collision and comprehensive coverage until you pay off the loan.
Before paying annually, check what each coverage option costs and whether you can save by paying in full. Think about what you could afford to pay for repairs or a replacement after a claim, then shop around to see if you can get similar coverage for less.
How Location Affects Annual Car Insurance Costs
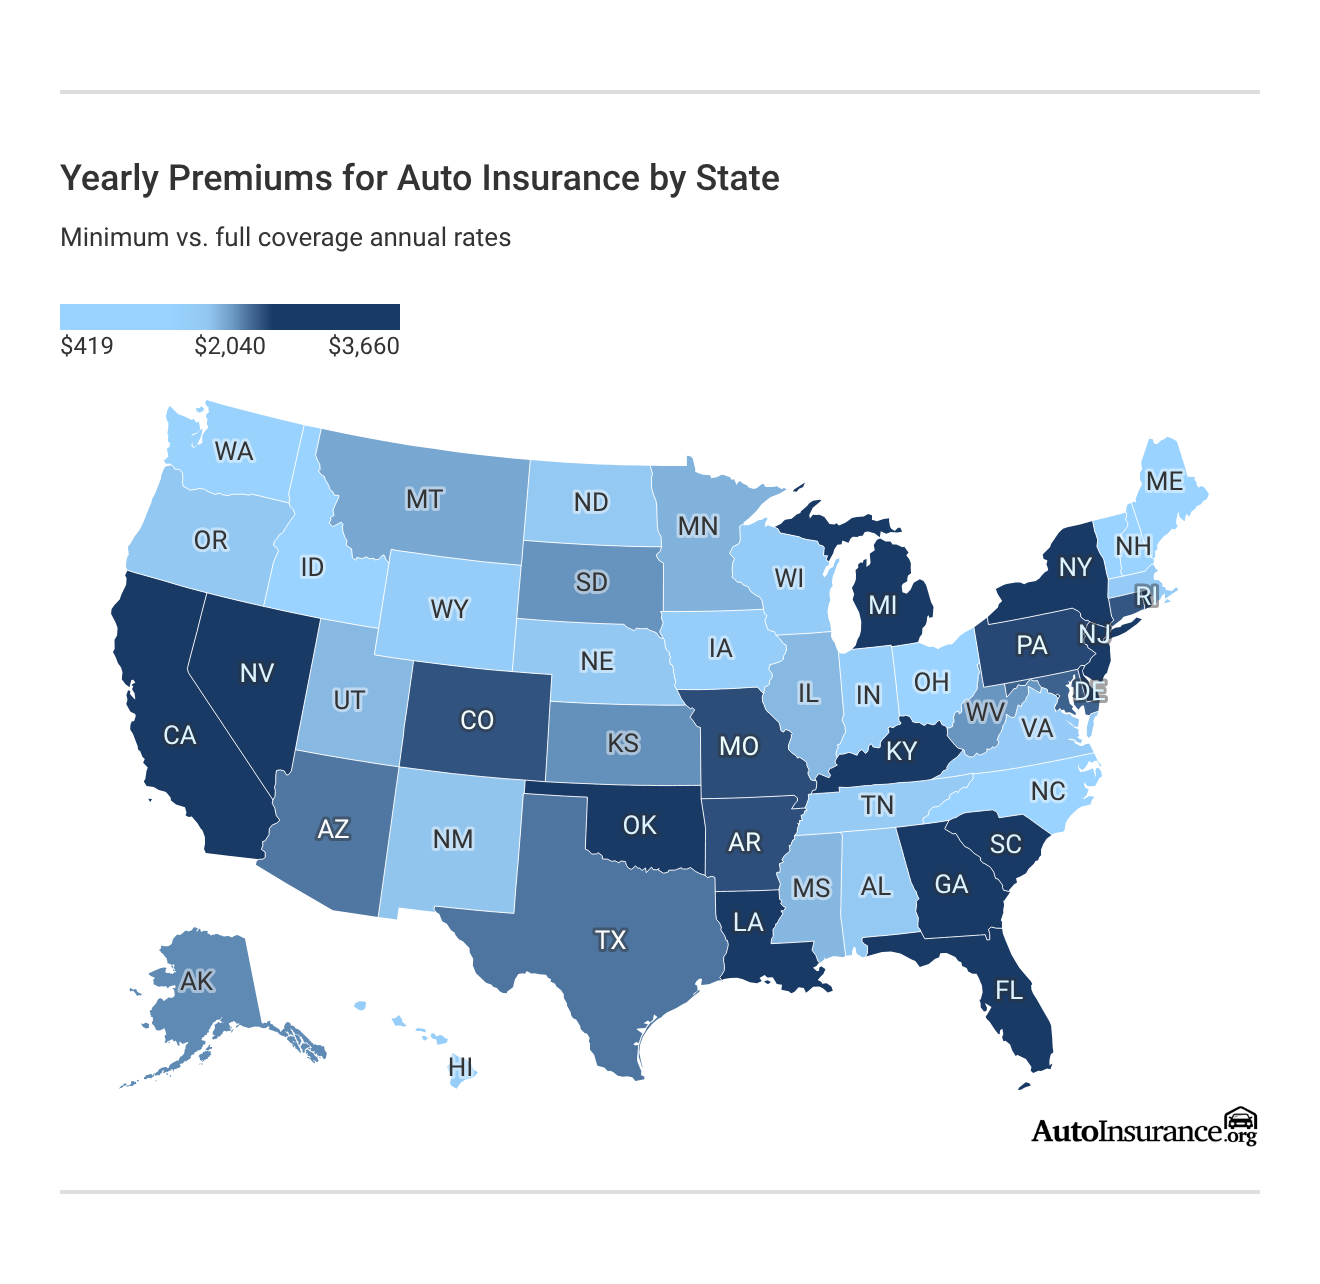
Where you live can make a difference in what you pay for car insurance. State insurance requirements, repair costs, and claim trends can all affect your annual premium.
Your state’s average yearly insurance cost can help you compare rates, but each insurer sets its own prices.
Auto insurance costs vary significantly by state. Louisiana has the highest average full-coverage premium at $3,660 per year, while Vermont has the lowest at $1,218. Wyoming has the cheapest minimum coverage at $419 annually.
Drivers comparing policies with annual payment options should check quotes from multiple insurers, since premiums and pay-in-full discounts vary by location and company.
If you’re paying more than the average for car insurance by state, review your coverage and deductible to see whether adjustments could lower your premium.
Learn More: Which states have the cheapest auto insurance rates?
How Your Credit Profile Affects Annual Car Insurance Rates
Your credit history can affect your car insurance costs. Before your policy renews, take a look at your financial profile to see if anything has changed.
Paying off debt or correcting errors on your credit report could help you qualify for a lower rate. You can also compare insurance prices from different companies to see whether you’re getting a good deal on annual coverage.
Yearly Premiums for Auto Insurance by Credit Score
| Company | Excellent (800+) | Good (670-799) | Fair (580-669) | Poor (<580) |
|---|---|---|---|---|
| Allstate | $936 | $1,045 | $1,267 | $1,734 |
| American Family | $828 | $921 | $1,167 | $1,526 |
| Auto-Owners | $624 | $661 | $774 | $954 |
| Erie | $672 | $714 | $846 | $1,034 |
| Farmers | $888 | $1,008 | $1,347 | $2,137 |
| Geico | $660 | $692 | $803 | $986 |
| Nationwide | $756 | $834 | $1,048 | $1,362 |
| Progressive | $852 | $945 | $1,153 | $1,607 |
| State Farm | $708 | $736 | $824 | $956 |
| Travelers | $840 | $927 | $1,140 | $1,763 |
The average yearly auto insurance cost varies by credit profile. These estimates cover a 45-year-old male driver with a clean record and minimum liability coverage, with rates grouped by insurer and credit score.
Actual costs vary by location, driving history, coverage requirements, and applicable state rules. Figures represent annual insurance costs, not necessarily premiums paid in a single yearly installment.
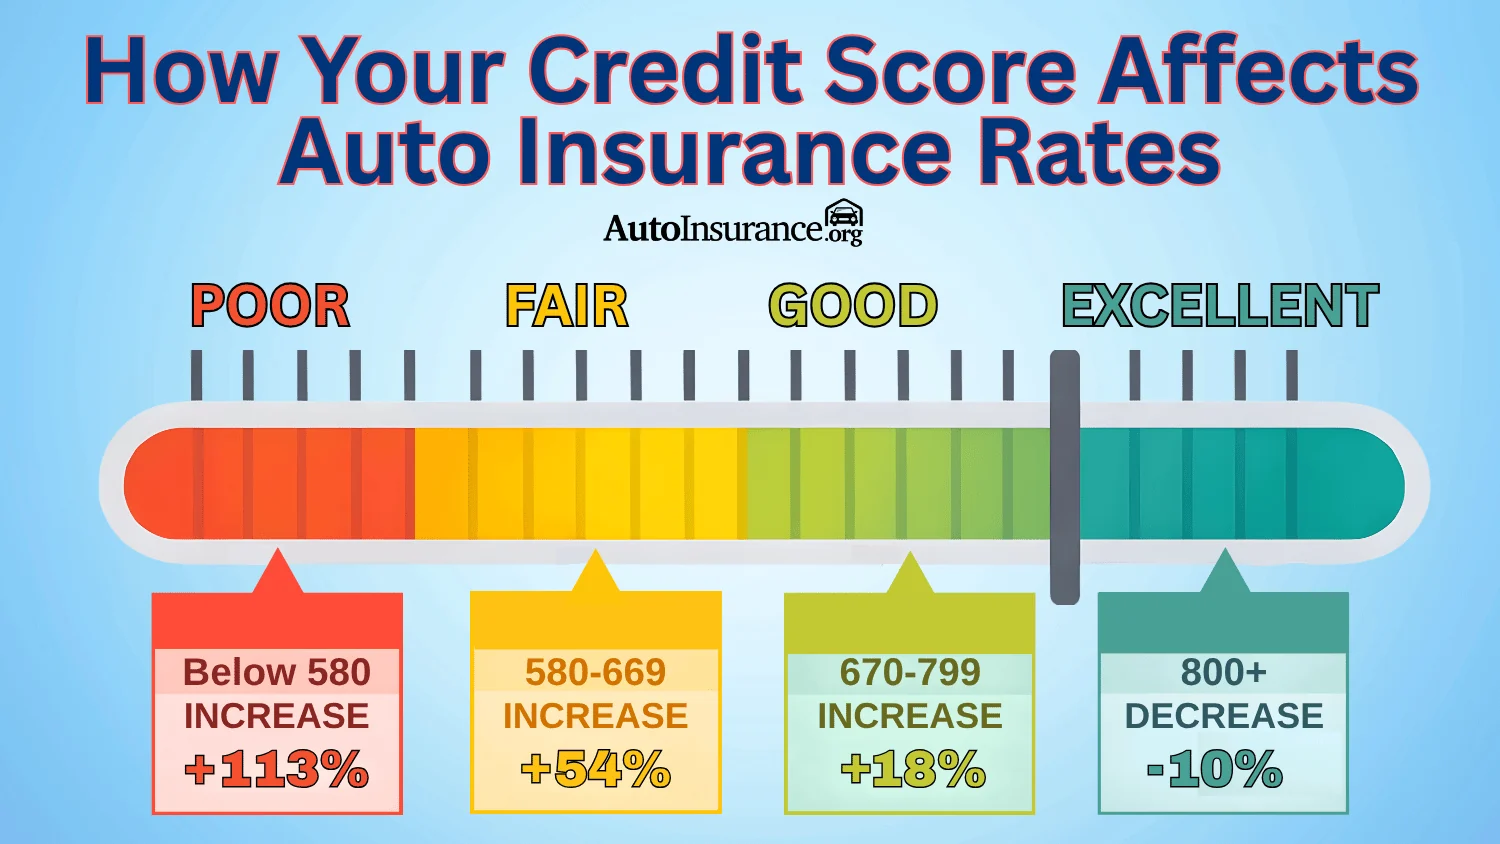
Auto insurance premiums increase as credit scores decline across all 10 companies. Auto-Owners has the lowest listed premium for excellent credit at $624 per year, while Farmers has the highest premium for poor credit at $2,137.
Drivers comparing annual payment options should also check whether insurers offer pay-in-full discounts, since the lowest yearly premium may not provide the greatest payment savings.
Insurers use credit-based insurance scores to predict claims. These aren’t the same scores lenders use. California, Hawaii, Massachusetts, and Michigan limit how credit affects auto insurance rates. Your driving record and coverage choices can still affect what you pay.
Compare Annual Car Insurance Costs After a Violation
A ticket or at-fault accident can affect your premium differently depending on how an insurer evaluates driving violations.
Speeding tickets and at-fault accidents can stay on your insurance record for several years, while a DUI may affect pricing longer.
Yearly Premiums for Auto Insurance by Driving Record
| Company | Clean Record | One Accident | One DUI | One Ticket |
|---|---|---|---|---|
| Allstate | $936 | $1,385 | $1,778 | $1,292 |
| American Family | $828 | $1,151 | $1,474 | $1,093 |
| Auto-Owners | $624 | $836 | $1,154 | $792 |
| Erie | $672 | $880 | $1,163 | $907 |
| Farmers | $888 | $1,305 | $1,723 | $1,288 |
| Geico | $660 | $1,003 | $1,386 | $1,063 |
| Nationwide | $756 | $1,081 | $1,550 | $1,270 |
| Progressive | $852 | $1,347 | $1,832 | $1,210 |
| State Farm | $708 | $880 | $1,289 | $913 |
| Travelers | $840 | $1,252 | $1,579 | $1,142 |
For a 45-year-old male driver with excellent credit, minimum coverage, and a clean driving record, Auto-Owners has the lowest yearly premium at $624. It also has the lowest listed premiums after one ticket ($792), one accident ($836), and one DUI ($1,154).
Drivers with violations should compare insurers based on their specific driving history, since surcharges vary by company and state. Paying the full policy premium upfront may also qualify for a discount.
Ask your insurer when a ticket or accident will stop affecting your premium. Comparing quotes before that surcharge expires can help you plan when to shop.Melanie Musson Published Insurance Expert
Drivers who need high-risk auto insurance should check which companies accept their violation history.
Approved defensive driving courses may provide premium reductions based on state rules and insurer requirements. To find coverage that fits your driving record and budget, review your insurance options.
Related: Cheap Auto Insurance for a Bad Driving Record
How Driver Demographics Affect Annual Car Insurance Pricing
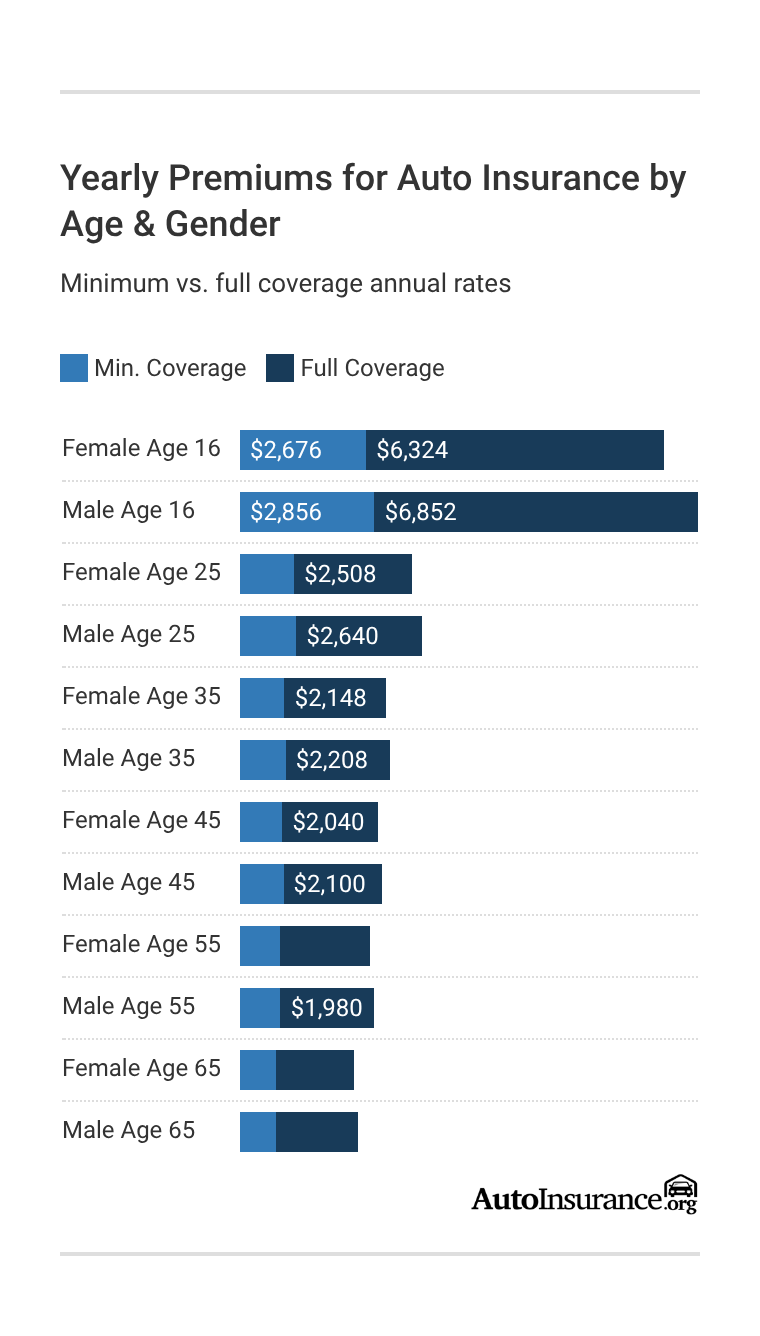
Your age and gender can influence your annual car insurance premium. Your location, vehicle, and coverage level also factor into your rate.
A birthday isn’t the only reason your premium can change. A claim, traffic violation, or adding a new driver can also affect your annual cost.
Auto insurance premiums generally decrease as drivers get older, with younger drivers paying the most for both minimum and full coverage.
Men typically pay more than women in the age groups shown, although the difference narrows with age. Drivers comparing annual car insurance payments should check rates from multiple insurers and ask about pay-in-full discounts, since savings vary by company.
Younger drivers may qualify for savings through approved driver training programs or good student discounts when they meet the insurer’s requirements.
Further Reading: Auto Insurance Rates by Age
Free Insurance Comparison
Compare Quotes From Top Companies and Save
Car Insurance Coverage and Savings
Two insurers may charge different premiums for similar coverage. Compare coverage limits, deductibles, and total annual costs to determine which policy offers better value.
You can also ask about insurance discounts that weren’t included in your original quote. This can help you find a policy that offers good protection without spending more than necessary.
Yearly Premium Auto Insurance Coverage
Start with the car insurance coverage your state requires, then consider what else makes sense for your vehicle and budget. Adding optional coverage can increase your premium, so the average yearly car insurance cost may not reflect what you’ll pay for your chosen protection.
The best car insurance companies have different policy options, so check what’s available before choosing your protection.
Liability, Collision, and Comprehensive Protection
Your state decides how much liability coverage you need to carry. If you cause an accident, that coverage helps pay for the other person’s injuries or property damage.
Collision and comprehensive coverage focus on your own car. Collision helps with repairs or replacement after a covered crash, while comprehensive covers things like theft, hail, fire, vandalism, and animal strikes.
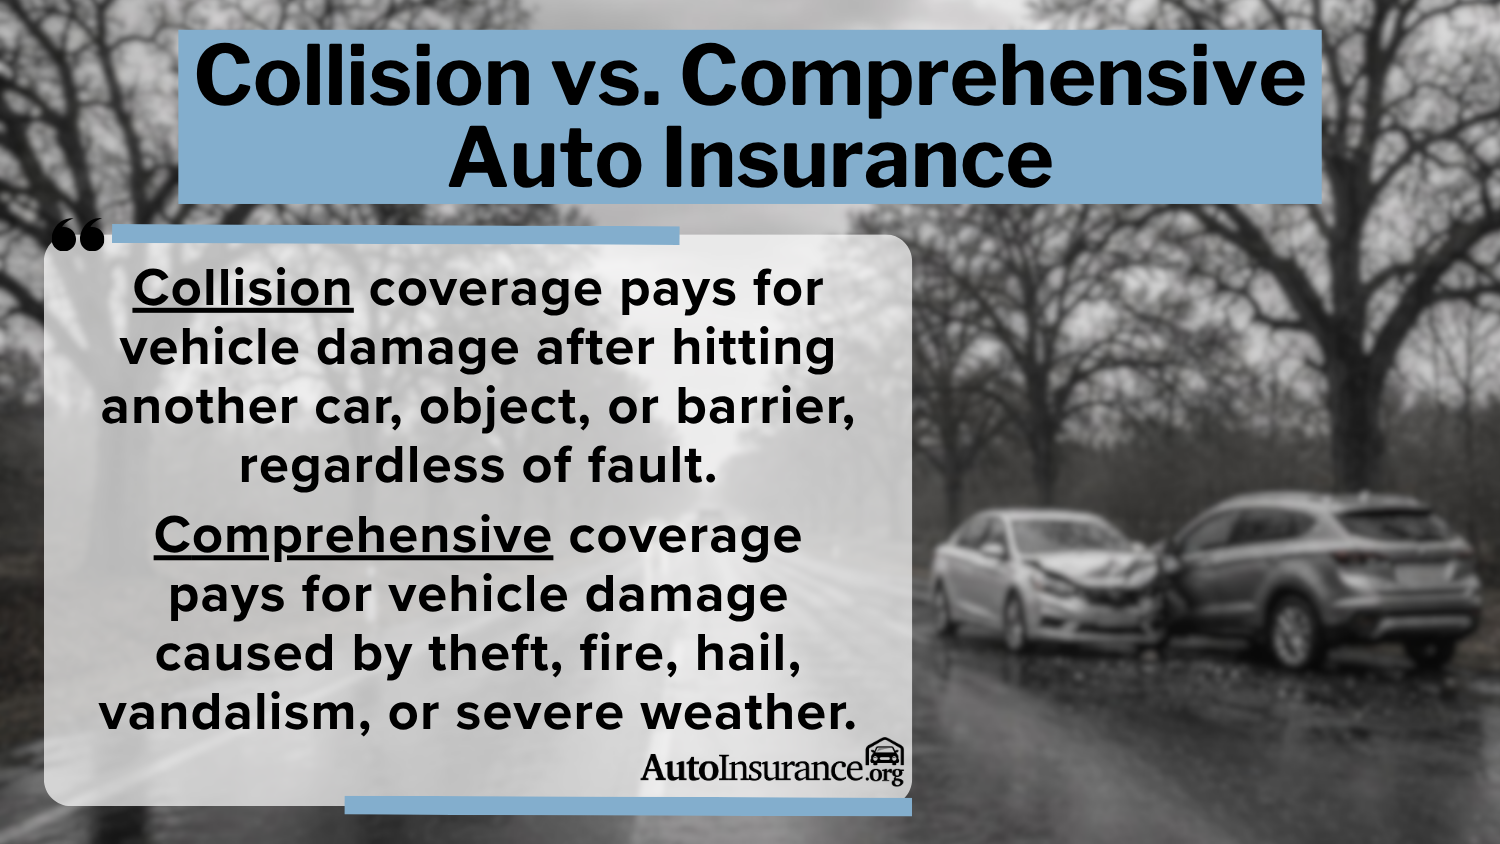
Financing or leasing a vehicle can affect the protection you need. Check your agreement to see if collision, comprehensive, or gap insurance is required.
Once the loan or lease ends, take another look at your coverage to see if it still fits your vehicle and budget.
Optional Protection for Your Annual Policy
Need a temporary car while yours is being repaired after a covered claim? Rental reimbursement can help with the cost. Roadside assistance can also come in handy if you need a tow, jump-start, flat tire change, fuel delivery, or lockout service.
If you’ve added custom wheels, a premium sound system, or other permanent upgrades, check whether your policy covers them.
When choosing additional coverage for your yearly auto insurance policy, consider:
- Gap Coverage: Helps pay the difference between your vehicle’s insurance settlement and the remaining loan or lease balance after a covered total loss.
- Medical Payments: MedPay helps pay eligible medical expenses for you and your passengers after an accident.
- Personal Injury Protection: Helps with eligible medical expenses and other covered costs after an accident.
- Uninsured and Underinsured Motorist: UM/UIM can pay for injuries caused by an uninsured or underinsured driver. Property damage coverage depends on policy and state.
Before adding optional protection, check what your current policy covers and what you could afford to pay after a claim.
If you’re paying for a full-year insurance policy upfront, ask your insurer how adding coverage would affect your cost.
Pay-in-Full Savings and Other Auto Insurance Discounts
Discount percentages are estimates or advertised maximums, not guaranteed savings. Eligibility, state availability, and rules for combining discounts vary by insurer. Check which savings apply to your policy before paying annually.
Bundling means buying another policy, such as home or renters insurance, from the same company. Low-mileage insurance discounts can also lower costs if you don’t drive many miles each year.
Top Discounts for Auto Insurance With Annual Payments
| Company | Bundling | Low-Mileage | Safe Driver | Usage-Based |
|---|---|---|---|---|
| Allstate | 20% | 30% | 18% | 30% |
| American Family | 40% | 20% | 18% | 35% |
| Auto-Owners | 20% | 30% | 15% | 30% |
| Erie | 15% | 30% | 15% | 30% |
| Farmers | 20% | 10% | 20% | 30% |
| Geico | 10% | 27% | 22% | 15% |
| Nationwide | 15% | 20% | 12% | 40% |
| Progressive | 25% | 30% | 10% | 30% |
| State Farm | 25% | 13% | 15% | 30% |
| Travelers | 16% | 20% | 15% | 30% |
Usage-based programs track driving habits such as speeding, hard braking, phone use, and quick acceleration. How you drive can affect the savings you receive, depending on the program.
Discounts aren’t the only way to lower your yearly premium. Your deductible, coverage choices, credit profile, and driving record can also affect what you pay.
- Check Rates Before Renewal: See how other insurers price similar coverage.
- Maintain a Clean Record: Avoiding tickets and at-fault accidents can help you avoid added costs at renewal.
- Raise Your Deductible: A higher deductible can lower your premium, but you’ll pay more after a covered claim.
- Recheck Your Protection: As your car ages, see if your current coverage still makes sense.
- Work on Your Credit: A stronger credit profile may help lower rates where credit-based insurance scoring is allowed.
Compare the total yearly cost, coverage limits, deductible, and available discounts before choosing a policy.
Before renewal, check personalized rates to see whether another insurer offers similar protection for less.
Find Out More: Best Companies for Bundling Home and Auto Insurance
How Yearly Auto Insurance Renewals Work
Your insurer reviews your rate when your policy renews. Your premium generally stays the same during your current term unless you change your policy.
A new ticket, at-fault accident, claim, or loss of a discount could affect what you pay for your next term.
Insurers may also adjust renewal rates because of rising repair costs, claims expenses, or changes in local insurance pricing, even if your driving record hasn’t changed.
Paying your premium upfront doesn’t prevent renewal increases. Your insurer can still change your rate when your next policy term begins.
Preparing for Your Yearly Policy Renewal
Your renewal notice shows the premium and coverage for your next policy term. Read through it before renewing to see whether anything has changed.
Check your deductible, coverage limits, listed drivers, and vehicle details to make sure everything is accurate. Look at your discounts, too, since losing one could increase your premium.
Before dropping collision or comprehensive coverage on an older vehicle, compare the annual premium with the car's value and what you could afford out of pocket.Dani Best Licensed Insurance Producer
If your renewal price is higher, ask your insurer what’s behind the increase. Comparing quotes is an important step in finding the best car insurance company for your next policy term.
Planning to pay annually? Check whether paying upfront costs less than making installments before your new term starts.
Get More Details: When does my auto insurance renew?
Factors Insurers Evaluate Before Renewal
Before renewal, insurers review changes to your driving record, claims history, vehicle, and policy details to determine your next premium.
Here are some of the key details insurers may consider before renewal:
- Claims History: Your CLUE report and recent claims can affect your renewal premium.
- Discount Eligibility: Insurers review your eligibility for multi-policy, multi-vehicle, safe driver, paperless, and telematics discounts.
- Driving Record: Includes new speeding tickets, at-fault accidents, DUIs, or other traffic violations.
- Household Drivers: Insurers review listed drivers and changes to your household that could affect your premium.
- Vehicle and Usage: Insurers consider your vehicle, annual mileage, commute, and usage when calculating your premium.
Keep your driver, vehicle, and policy details current so your insurer has accurate information when setting your next premium. A clean driving record can also help you avoid surcharges tied to tickets or at-fault accidents.
If your price goes up, ask your insurer what changed and whether any savings are available. You can also check rates from other insurers before deciding whether to renew.
10 Best Car Insurers Offering Yearly Billing
Erie, Nationwide, and State Farm lead our rankings for yearly premium auto insurance. Erie stands out for rate stability, Nationwide for low mileage, and State Farm is best for discounts with its variety of savings programs.
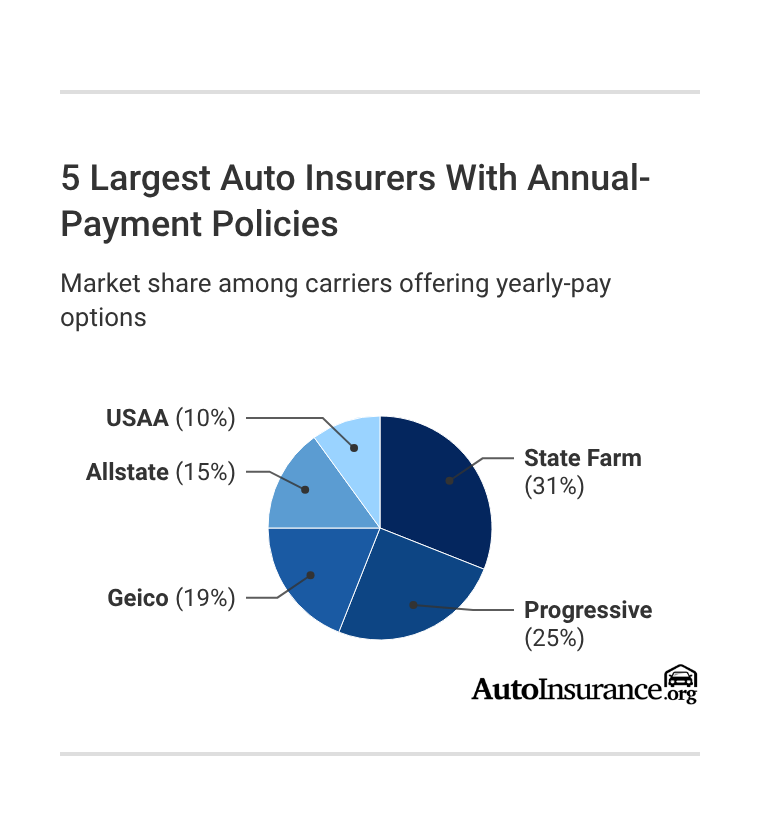
The five largest companies shown below account for different shares of this selected insurer group. Market share provides company-size context but does not determine our annual-payment rankings.
State Farm, Progressive, Geico, Allstate, and USAA are among the largest auto insurers offering annual payment options. The percentages show each company’s relative share among these five insurers, rather than its share of the entire U.S. auto insurance market.
Market share does not indicate which insurer offers the lowest yearly premium or the largest pay-in-full discount.
Check the cheapest car insurance companies if keeping costs down is a priority. Before choosing an insurer, compare claims service, available discounts, coverage, and annual costs.
#1 – Erie: Top Overall Pick
Pros
- Rate Lock Protection: Erie’s Rate Lock can help prevent premium increases for eligible policyholders, subject to program terms and qualifying policy changes.
- Diminishing Deductible: Each claim-free year lowers your collision deductible by $100, up to $500.
- First Accident Forgiveness: Your first at-fault accident won’t trigger a surcharge after three years with Erie.
Cons
- Limited State Availability: Our Erie insurance review shows coverage is limited to 12 states and Washington, D.C.
- Agent-Based Service: Buying or updating coverage generally requires working with a local Erie agent.
#2 – Nationwide: Best for Low Mileage
Pros
- SmartMiles Pricing: SmartMiles combines a base rate with a mileage charge, so driving less can reduce costs.
- SmartRide Discount: Safe driving with SmartRide can save you up to 40%. Related: Nationwide Insurance Review
- Driving Feedback: SmartRide shows how you’re doing by tracking mileage, braking, acceleration, idle time, and nighttime driving.
Cons
- Seven-State Exclusion: SmartMiles isn’t available in Alaska, Hawaii, Louisiana, Michigan, North Carolina, New York, and Oklahoma.
- Variable Monthly Cost: Payments can change based on mileage recorded during the previous billing cycle.
#3 – State Farm: Best for Discount Variety
Pros
- Extensive Savings Programs: Drive Safe & Save, Steer Clear, Good Student, and multi-policy discounts provide several ways to save.
- Large Local Agent Network: State Farm has about 19,000 agents available to help with coverage changes and policy questions.
- Exceptional Financial Strength: State Farm holds an A+ AM Best Financial Strength Rating, indicating a strong ability to meet financial obligations.
Cons
- Discount Eligibility Requirements: Savings depend on factors such as driving history, location, and individual program requirements.
- State-Specific Coverage Options: Our State Farm insurance review shows coverage and discount availability can differ by state.
#4 – Auto-Owners: Best for Agent Support
Pros
- Personalized Agent Guidance: Independent agents help customers choose coverage based on their vehicles and insurance needs.
- Common Loss Deductible: When the same covered event damages your home and vehicle, you may only have to pay one deductible.
- Collision Coverage Advantage: The collision deductible may be waived when an accident involves another vehicle insured by Auto-Owners.
Cons
- Agent Purchase Required: Policies generally must be purchased and updated through an independent agent rather than entirely online.
- Limited Availability: Coverage is available in 26 states rather than nationwide. Explore More: Auto-Owners Insurance Review
#5 – American Family: Best for Loyalty Rewards
Pros
- Customer Loyalty Discounts: Long-term customers may qualify for savings based on how long they’ve stayed with American Family.
- KnowYourDrive Program: Safer driving recorded through KnowYourDrive may lead to additional savings.
- Generational Discount: Customers with parents who have American Family coverage may qualify for a generational discount.
Cons
- Limited State Availability: As noted in our American Family insurance review, policies are sold in 19 states.
- Program Availability Varies: Discounts and rewards depend on state regulations and individual eligibility.
#6 – Geico: Best for Online Savings
Pros
- Online Quote Savings: Qualifying customers may receive a discount when they get their Geico quote online.
- Military and Federal Discounts: Qualifying military members and federal employees may receive additional policy discounts.
- Mechanical Breakdown Insurance: Eligible newer vehicles can get protection for certain mechanical repairs beyond the manufacturer’s warranty.
Cons
- Primarily Digital Service: Policy management and claims support are largely handled online or by phone rather than through local offices.
- Claims Satisfaction: Geico received 697 out of 1,000 for claims satisfaction. See More: Geico Insurance Review
#7 – Allstate: Best for Deductible Cuts
Pros
- Deductible Rewards: Allstate cuts your collision deductible by $100 at signup and another $100 each accident-free year, up to $500, per the Allstate insurance review.
- Home and Auto Savings: Combining qualifying home and auto policies can provide savings of up to 20%.
- Drivewise Savings: Completing at least 50 Drivewise trips can qualify participants for driving-based renewal savings.
Cons
- Bundle Savings Vary: Advertised savings aren’t available everywhere, and the discount amount depends on the state.
- Drivewise Trip Minimum: At least 50 recorded trips are required before a Drivewise score can qualify for savings.
#8 – Travelers: Best for Driver Tracking
Pros
- 90-Day Tracking: IntelliDrive tracks your driving for 90 days, so you know exactly how long the program monitors your habits.
- Trip Corrections: You have 10 days to fix trips the app incorrectly records as yours.
- Driving Feedback: You can review your recorded driving habits while using IntelliDrive. Discover More: Travelers Insurance Review
Cons
- Rate Can Increase: Riskier driving with IntelliDrive 365 can raise your rate by up to 45% where allowed.
- 500-Mile Minimum: You need to record at least 500 miles within 90 days to receive a score.
#9 – Farmers: Best for Policy Flexibility
Pros
- Multiple Coverage Add-Ons: Farmers offers OEM parts, rideshare, glass, residual debt, and other optional coverages.
- Residual Debt Protection: Farmers can pay up to 25% above your vehicle’s actual cash value toward the remaining balance, as explained in our Farmers insurance review.
- OEM Parts Coverage: Farmers may pay for original manufacturer parts if your qualifying vehicle is up to 10 years old.
Cons
- Accident Forgiveness Limit: Farmers only forgives one at-fault accident every three years for qualifying customers.
- Coverage Varies by State: Some coverage options aren’t available everywhere, so what you can add depends on where you live.
#10 – Progressive: Best for Risky Drivers
Pros
- SR-22 Support: Progressive can file an SR-22 when required after certain serious driving violations.
- Continuous Coverage Discount: Your previous insurance history may qualify you for savings when switching to Progressive.
- Accident Forgiveness: Qualifying claims of $500 or less won’t result in a rate increase under Small Accident Forgiveness.
Cons
- SR-22 Filing Cost: You’ll generally pay an additional fee when Progressive files an SR-22 for you. Read More: Progressive Insurance Review
- Limited Local Agents: Most Progressive customers handle their coverage online or by phone rather than with a local agent.
Free Insurance Comparison
Compare Quotes From Top Companies and Save
Getting the Best Auto Insurance With Annual Payments
Finding the best auto insurance with annual payments also means knowing what happens to your money if your plans change.
Before paying upfront, ask your insurer how cancellations, refunds, and midterm policy changes work.
You can also review the types of auto insurance available if your needs change during the policy period.
Ask your insurer how adding or removing coverage would affect a premium you’ve already paid.
If you pay for a full year and cancel early, your refund may depend on the insurer's cancellation rules. Ask whether any fees apply.Jeff Root Licensed Insurance Agent
When you compare the best car insurance companies, check how each handles policy changes after you’ve paid in full. Find out whether you’ll owe an additional amount or receive a refund if your premium changes.
Compare quotes from several insurers to find the best auto insurance prices for the coverage you need.
Frequently Asked Questions
Which auto insurance company is best for yearly premium auto insurance?
Erie is our top pick because it offers competitive rates, dependable claims service, and its Rate Lock feature in many states.
Who offers the cheapest yearly premium auto insurance?
Auto-Owners, Geico, and Erie are among the best options for yearly premium auto insurance, but the cheapest company depends on your location, vehicle, and driving history. Compare quotes to find your lowest annual rate.
Compare the best yearly premium auto insurance available in your area by entering your ZIP code.
What insurance companies offer 12-month auto insurance policies?
Erie, Nationwide, and State Farm offer 12-month auto insurance policies in certain states. Since availability varies by location, comparing quotes can help you find affordable auto insurance rates online.
Is paying annually the same as having a 12-month auto insurance policy?
No. Annual payment refers to how often you pay your premium, while a 12-month policy refers to how long the insurance term lasts. Some insurers let you pay a six-month policy in full, and others allow installments on a 12-month policy.
How much is the average annual auto insurance premium?
Average annual auto insurance premiums depend on your age, location, and coverage level. For example, the chart above shows average full-coverage premiums of $2,040 per year for 45-year-old women and $2,100 for 45-year-old men. Compare personalized quotes to find your own annual rate.
What is a good annual rate for car insurance?
A good rate is one that provides the coverage you need at a competitive price compared with similar drivers in your area. You can get multiple auto insurance quotes to see if you’re paying a fair annual premium.
How can I lower my yearly auto insurance premium?
One of the easiest ways to lower your yearly premium is to compare quotes before renewing your policy. You can also save by maintaining a clean driving record, choosing a higher deductible, and taking advantage of discounts.
Use our free quote comparison tool to see what you could save on car insurance with annual payment options.
Is a $500 or $1,000 deductible better for your yearly premium?
A $1,000 deductible usually means a lower premium, while a $500 insurance deductible helps keep your out-of-pocket costs lower after a covered claim. Pick the option that best fits your budget.
Does my deductible reset every year for yearly premium auto insurance?
No. Auto insurance deductibles generally apply to individual collision or comprehensive claims, rather than resetting annually. Your deductible amount stays the same at renewal unless you change it or a policy benefit reduces it.
What is the downside to having a high deductible for yearly premium auto insurance?
A higher deductible can lower your premium, but you’ll generally pay more out of pocket after a covered collision or comprehensive claim. Insurers may subtract the deductible from your claim payment.
Is a $5,000 deductible for comprehensive and collision coverage worth it?
How does age affect yearly auto insurance premiums?
Why is my yearly auto insurance premium so high with a clean driving record?
Why is Geico’s yearly auto insurance premium lower than some competitors’?
Why is Progressive’s yearly auto insurance premium so affordable?
Is AAA cheaper than Geico for yearly premium auto insurance?
Does car color affect your yearly auto insurance premium?
How can I compare auto insurance company complaints?
Which auto insurance companies have the highest claim denial rates?
Does yearly auto insurance cover windshield replacement?
What should you avoid saying to your auto insurance company after an accident?
Get a FREE Quote in Minutes
Insurance rates change constantly — we help you stay ahead by making it easy to compare top options and save.